Wise Multi-Asset Income
Fund Ratings
Investment Objective
The Fund aims (after deduction of charges) to provide:
- an annual income in excess of 3%: and
- Income and capital growth (after income distributions) at least in line with the Consumer Price Index ("CPI"), over Rolling Periods of 5 years.
Fund Attributes
- A flexible, diversified portfolio that can invest in all asset classes.
- Targets an attractive and growing level of income.
- The portfolio invests both direct and through open and closed-ended funds.
- Adopts a value biased investment approach.
- Pays monthly
Investor Profile
- Seek an attractive level of income and the prospect of long term capital growth.
- Accept the risks associated with the volatile nature of an adventurous multi-asset investment.
- Plan to hold their investment for the long term, 5 years or more.
Key Details
| Target Benchmark | UK CPI |
|---|---|
| Comparator Benchmark (Sector) | IA 40-85% Investment Sector |
| Launch date | 3rd October 2005 |
| Fund value | 95.1 million |
| Holdings | 36 |
| Historic yield | 4.30% |
| Div ex dates | First day of every month |
| Div pay dates | Last day of following month |
| Valuation time | 12pm |
- Past performance is not a guide to the future and outperforming target benchmarks is not guaranteed.
- The historic yield reflects distributions over the past 12 months as a percentage of the price of the B share class as at 31st August 2026. Investors my be subject to tax on their distributions.
Dividend Information
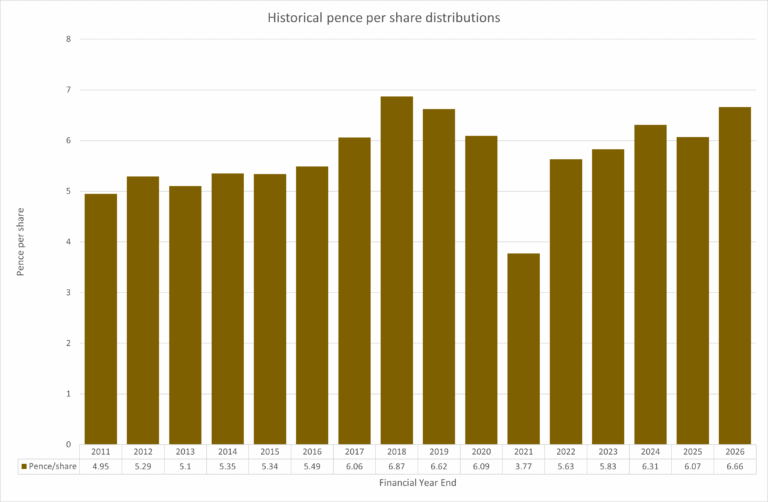
Pence/share figures relate to the fund’s financial year ending in February of the relevant year.
For a breakdown of the dividends, please click here
Investment Portfolio - August 2026
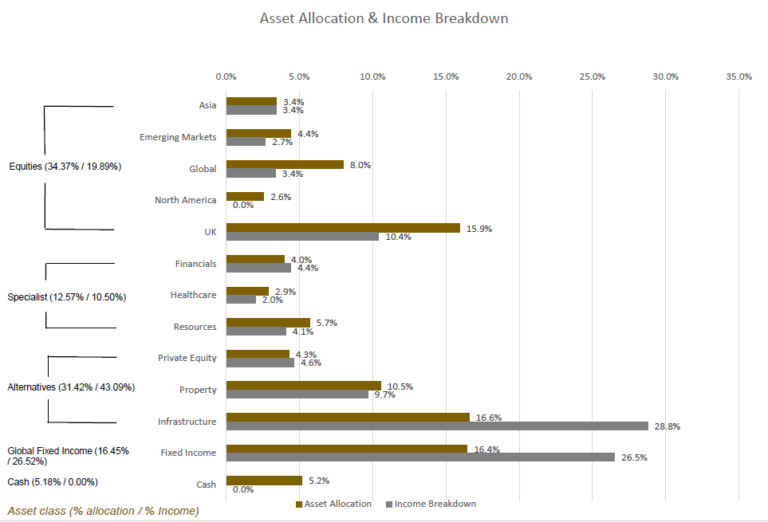
Source – Wise Funds Limited as at 31st August 2026.
The asset allocation is derived from the full portfolio holdings and the income data shows where the the current yield is being accrued from by asset class.
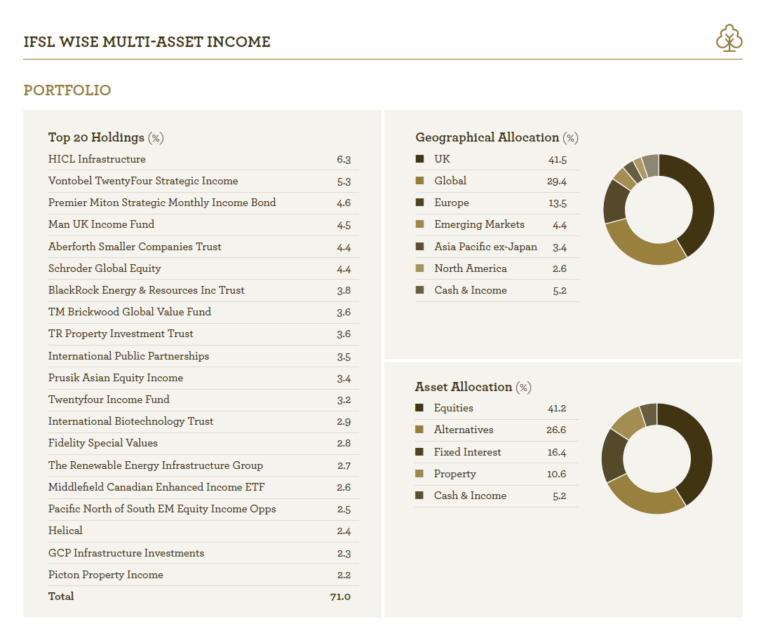
- Past performance is not a guide to the future
- Data as at 31st August 2026
Share Class Information
| | B Acc (Clean) | B Inc (Clean) | W Acc (Institutional) | W Inc (Institutional) |
|---|---|---|---|---|
| Sedol Codes | B0LJ1M4 | B0LJ016 | BD386V4 | BD386W5 |
| ISIN Codes | GB00B0LJ1M47 | GB00B0LJ0160 | GB00BD386V42 | GB00BD386W58 |
| Minimum Lump Sum | £1,000 | £1,000 | £50 million | £50 million |
| Initial Charge | 0% | 0% | 0% | 0% |
| IFA Legacy Trail Commission | Nil | Nil | Nil | Nil |
| Investment Management Fee | 0.75% | 0.75% | 0.50% | 0.50% |
| Operational Costs | 0.17% | 0.17% | 0.17% | 0.17% |
| Look-through Costs | 0.23% | 0.23% | 0.23% | 0.23% |
| Ongoing Charges Figure 12 | 1.15% | 1.15% | 0.90% | 0.90% |
All performance is still quoted net of fees.
- The Ongoing Charges Figure is based on the expenses incurred by the fund for the period ended 28th February 2026.
- Includes Investment Management Fee, Operational costs and look-through costs.
The figures may vary year to year
Fund Commentary - August 2026
Investors were increasingly focused on interest rates and longer-term government borrowing costs during August. In the US, surprisingly weak employment figures initially encouraged hopes that the Federal Reserve (Fed), the US central bank, might not need to raise rates. The economy lost jobs in July, contrary to expectations, while previous months were revised lower. Easing inflation data also provided some reassurance. However, stronger business surveys, pressure from energy prices and comments from Fed Chair Kevin Warsh describing inflation as “concerning” subsequently changed the mood, with expectations of a September rate rise rebuilding towards the month-end.
.
A similar tension between slowing growth and persistent inflation was evident elsewhere. UK economic growth remained positive, but the labour market continued to soften while inflation accelerated, largely reflecting higher energy costs. The Bank of England left rates unchanged, with markets expecting only limited further tightening. Eurozone growth was somewhat stronger than expected, while higher energy prices increased expectations of another European Central Bank rate rise. China was a notable weak spot, with disappointing domestic demand and investment despite continued strength in exports. Japan saw the clearest change in interest-rate expectations, with rising inflation increasing the likelihood of a September rate rise and pushing government bond yields higher.
Increasing government indebtedness became an important influence on longer-term borrowing costs. Investors lending to governments for many years require compensation not only for the expected path of interest rates, but also for uncertainty surrounding inflation and public finances. US government debt passed $40 trillion during August, having increased by around $3 trillion over the previous year, while annual interest costs have risen to around $1 trillion. Concerns over government borrowing were not confined to the US, with long-term yields reaching levels not seen for many years across several developed markets. This matters because higher government bond yields increase borrowing costs throughout the economy and from an investment standpoint make other income-producing investments relatively less attractive. The US Treasury responded to pressure on longer-term borrowing costs by increasing its purchases of longer-dated government bonds. The move highlighted a potential conflict between different arms of US policy: the Fed remained concerned about inflation and the possibility that interest rates might need to rise, while the Treasury was acting to reduce longer-term borrowing costs. In addition, there was unusual intervention in currency markets, with the US joining the Japanese authorities in buying yen for the first time in almost 30 years in an attempt to strengthen the currency.
Despite edging closer to the US mid-term elections, the conflict in Iran remains unresolved and continues to be a significant headwind in the battle to reduce inflation. Hopes that an agreement might restore more normal traffic through the Strait of Hormuz periodically reduced oil prices, but negotiations failed to produce a permanent settlement and tensions increased again towards month-end. Although oil prices ultimately fell over August, disruption to energy markets continue to create uncertainty. Despite this challenging backdrop, global equity markets remained remarkably resilient. US and Japanese equities were particularly strong, while emerging markets and Asia also made headway. The UK lagged the broader global market, although smaller and medium-sized companies performed considerably better. Strong corporate earnings and renewed enthusiasm surrounding artificial intelligence helped highly valued growth and technology shares recover strongly from their July weakness. One factor behind the speed of this reversal was the removal of some of the forced selling that had affected technology shares in July. AI-focused hedge fund Situational Awareness lost around two-thirds of its portfolio value that month and was forced to reduce its leverage and public equity exposure substantially. With this source of selling pressure removed, many AI-related shares recovered strongly in August. This provides some context for the sharp reversal in market leadership over the last two months.
Against this backdrop, the IFSL Wise Multi-Asset Income Fund rose 1% during August, slightly behind the IA Mixed Investment 40–85% Shares sector, which rose 1.8%. While most areas of the portfolio contributed positively, some of the differentiated positioning which had been beneficial during July did not fully participate in the rebound in expensive growth shares. Our international value-oriented funds, including Schroder Global Equity Income, Brickwood Global Value and our emerging-market managers, delivered positive returns but generally lagged their respective markets. Commodity-related investments were the standout performers. BlackRock World Mining, which has significant exposure to gold producers, rose over 20%, benefiting from the sharp rise in gold and strong underlying asset performance. Gold benefited from geopolitical uncertainty, concerns over government finances and a weaker US dollar. BlackRock Energy & Resources also performed well through its broader exposure to energy and industrial commodities. Our UK equity holdings also performed well. Aberforth Smaller Companies and Odyssean Investment Trust benefited from the strength of UK smaller and medium-sized companies, while Finsbury Growth & Income continued its recent recovery in performance. International Biotechnology Trust was another standout, rising around 11%, helped by strong underlying investment performance and a narrowing of its discount. The broader biotechnology sector was also supported by M&A (Mergers and Acquisitions) activity and encouraging clinical developments, including positive late-stage results from Moderna and Merck’s personalised melanoma cancer vaccine. Infrastructure was another positive contributor. HICL Infrastructure reaffirmed its dividend targets and continued buying back shares at a substantial discount. The Renewables Infrastructure Group reported strong cash generation, reaffirmed its dividend and continued its asset disposal and share buyback programmes, while Foresight Environmental Infrastructure reported positive underlying returns and renewable generation ahead of budget.
Property was the main area of weakness, reflecting pressure from longer-term bond yields rather than any deterioration in the underlying company news. Middlefield Canadian Enhanced Income was held back by weakness in property and energy holdings, while Prusik Asian Income suffered from weakness among its Hong Kong investments.
During the month, we initiated a holding in Schroder Real Estate Investment Trust. The trust owns a predominantly multi-let industrial and retail warehouse portfolio, where active asset management and rental growth provide scope to increase earnings. The company offers a highly attractive yield today with scope for future growth and limited refinancing risk in the near term. Elsewhere, we added to ICG Enterprise and Finsbury Growth & Income which we funded through a reduction in our GCP Infrastructure holding.